standard cost
Quick Summary
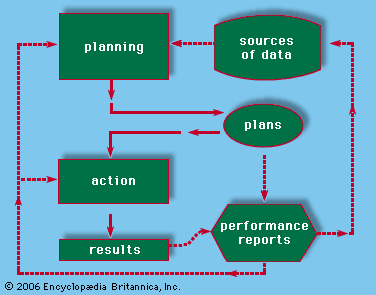
A standard cost is a predetermined cost used for comparison with actual costs, assuming normal operating conditions. In accounting, cost finding involves estimating the expenses of producing products or services. This can be done historically or predictively.12
Methods like process costing and job-order costing are used to determine these costs. Process costing averages costs over a production period for uniform outputs, while job-order costing tracks costs for specific batches or jobs, distinguishing between direct (prime) costs and indirect (overhead) costs.2
Activity-based costing identifies cost drivers and estimates costs based on specific activities. Standard costs are often established as estimates of average costs for materials, operations, and products, serving as benchmarks for performance evaluation. Accounting principles, such as GAAP in the U.S., guide how these costs are measured and reported, often using historical cost as a basis.23
Ask Britannica AI about this topic
Britannica doesn't have a full article on this topic, so we've curated a list of our relevant coverage.